Summarize this article with AI
In Brief
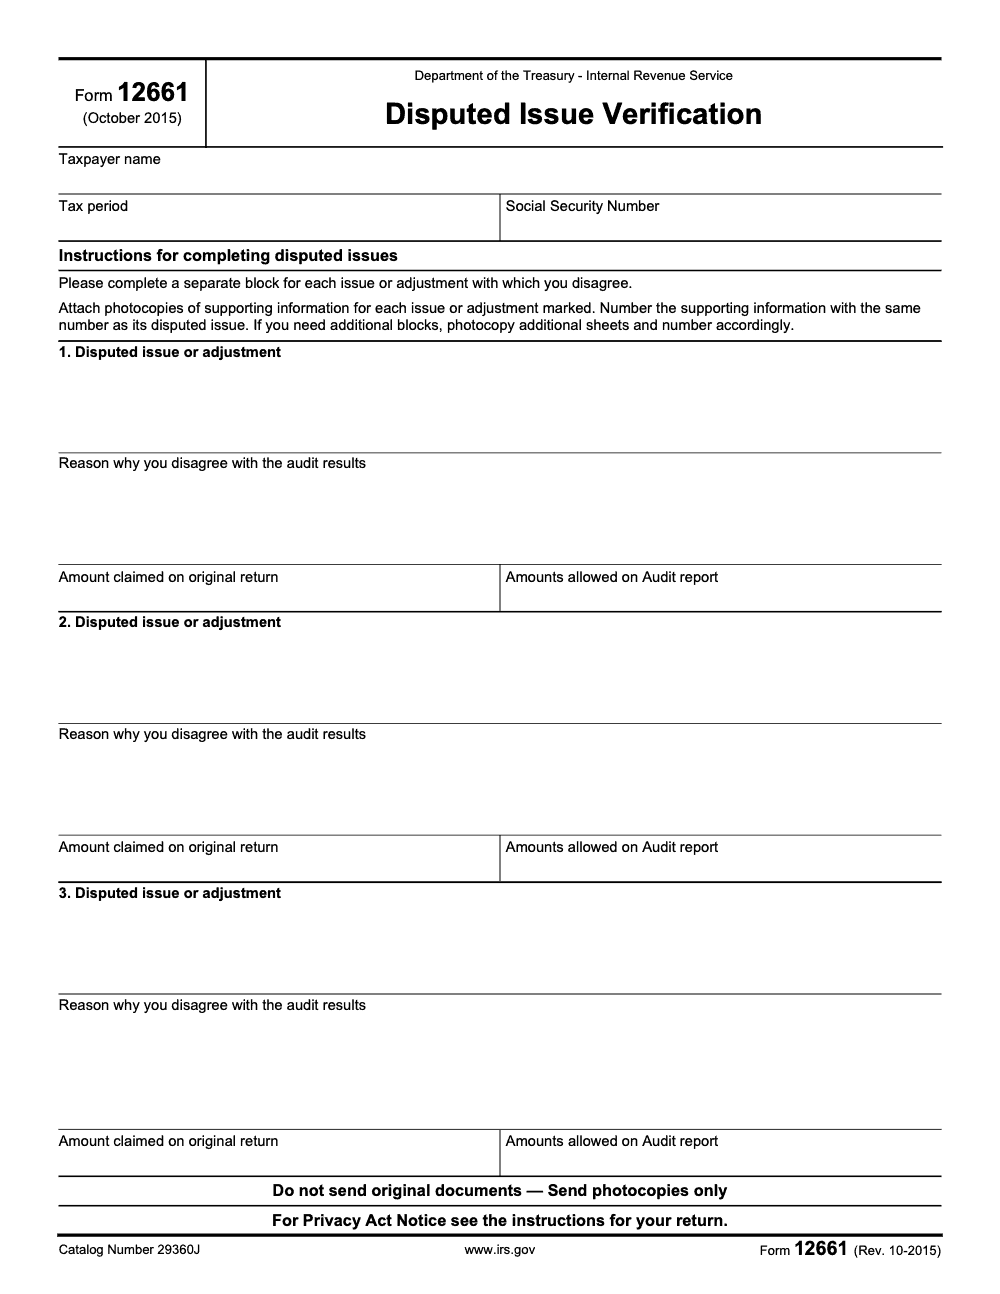
Form 12661, Disputed Issue Verification (Rev. October 2015), is the IRS support form a taxpayer uses to list each audit adjustment they disagree with – one numbered block per disputed issue, with the amount claimed on the original return, the amount allowed by the auditor, and a written reason for disagreement (per IRS Form 12661 instructions, Rev. 10-2015). The form has no printed filing deadline; submit it inside the response window stated on the IRS audit letter or audit reconsideration acknowledgement, attach numbered photocopies of every supporting document, and never send originals.
Audit reconsideration does not slot into a fixed calendar window the way payroll filings do. Form 12661 attaches to an open IRS letter, so the deadline that governs lives inside that letter, and a single client can land several disputed items at once, each one needing its own numbered block, its own written reason for disagreement, and its own labeled stack of photocopies.
Form 12661, Disputed Issue Verification (Rev. October 2015), is how a taxpayer itemizes the Form 4549 adjustments they think are wrong while tax still stands unpaid. Submit by mail, fax, or the IRS Document Upload Tool at irs.gov/examreply, and expect acknowledgment around 30 days. If the balance is already paid in full, audit reconsideration is the wrong door and Form 1040-X is the refund path instead.
Key Takeaways
- Form 12661, Disputed Issue Verification, is the IRS form you can use to itemize the disputed adjustments inside an audit reconsideration package after an exam when specific Form 4549 adjustments are wrong and tax remains unpaid (the reconsideration request itself is typically initiated by a written request letter following Pub 3598 procedures, with Form 12661 listing each disputed item).
- You must include new or previously unreviewed documents tied to each disputed item. Think copies of passport stamps, payroll, deposits, leases, foreign returns, and calculations.
- Do not use audit reconsideration if there is a final court decision, a binding closing agreement, or if you paid in full. For paid assessments, use Form 1040‑X to claim a refund instead.
- Submit by mail, fax, or the IRS Document Upload Tool at irs.gov/examreply, addressed to the office that handled your audit. Expect acknowledgment around 30 days, though complex cases take longer.
- If the result is adverse, you may request an Appeals conference or, if paid, pursue a refund claim. Collections may continue unless the IRS places a hold.
What Form 12661 Is, When It Applies, and Who Qualifies
Form 12661 is a simple, structured way to spell out exactly what parts of the audit you dispute, why the IRS’s determination is wrong, and what evidence changes the outcome. It is used after the audit is closed, when the balance is still unpaid, and when you can provide information the IRS did not review the first time. You can either write a letter or complete Form 12661 to organize your request, but the form keeps everything aligned with the audit report.
The IRS’s own guidance reinforces three pillars for acceptance: the audit was closed with an unpaid assessment, you can show new information or a computational error, and you send the request to the office that handled the exam. Examiners are instructed to review your Form 4549, screen within several workdays, and work the case in CEAS/RGS with documented workpapers.
When You Should Not Use Form 12661
There are bright lines. If a court has entered a final determination on liability, or if you signed a binding closing agreement under IRC 7121, reconsideration is generally off the table because those outcomes carry statutory finality. Similarly, if the assessment is already fully paid, you pivot to a refund claim, usually via Form 1040‑X for individuals.
In practice, here is the quick test you can apply before you gather a single exhibit:
- Final court decision or closing agreement on the same issue and year, including Form 906 or Form 870‑AD, means no reconsideration.
- Fully paid balance means file a claim for refund, not Form 12661.
- No new information, just disagreement, means your chances drop. The IRS wants documentation it did not review previously or clear evidence of error.
The Submission Channels That Work Best
You have three practical ways to send a reconsideration package:
- Document Upload Tool, recommended by the IRS at irs.gov/examreply. This is the fastest route for many correspondence exams. Label every file with TIN and tax year.
- Mail to the address on your audit letter. Keep copies and consider certified mail with return receipt.
- Fax to the number on your exam notice. Put identifying info on every page to avoid misrouting.
There is also an IRS-hosted digital wizard for Form 12661 that lets you submit electronically or download a completed PDF for mail or fax, which can speed assembly and reduce keying mistakes.
Who This Guide Is For
You are likely a partner, EA, or manager balancing deadlines, reviews, and client urgency. You do not need more theory. You need a repeatable way to package new facts, link them to the Form 4549 lines, and move the IRS from “no” to “yes” without burning hours. That is exactly what the next sections deliver.
You win reconsiderations with evidence, organization, and a clear tie to the audited adjustments. Everything else is noise.
Documents To Gather For A Strong Reconsideration Package
Start with the audit report. Highlight each disputed line on Form 4549. For every line, collect only the documents that prove your correction, then label and cross‑reference them to the exact line and year. The IRS emphasizes that new or previously unsubmitted information is what moves the needle. Copies only, never originals.
Common exhibit sets that work:
- Physical presence and housing for Form 2555, FEIE, or housing exclusion, supported by passport entry and exit stamps, itineraries, leases, utilities, and employer letters.
- Foreign tax credit backup, including foreign returns, payment receipts, and assessments from the foreign tax authority.
- Income proof that ties deposits to contracts and payroll, backed by bank statements, pay stubs, and employment agreements.
Organization And Cross‑Referencing That Reviewers Love
Package your case like this:
- Cover letter with a one‑page index of disputes, showing the Form 4549 line, your corrected amount, and exhibit numbers.
- Exhibit binder or PDF with bookmarks by issue, each page watermarked with TIN and tax year, and each exhibit labeled to the matching dispute number.
- Calculations for corrected amounts, such as updated Form 2555 or FTC worksheets, with footnotes pointing to the evidence pages.
- A simple timeline that lists travel dates, payments, IRS notices, and why the information was unavailable during the audit.
Quick Reference Table
| Disputed Area | What The IRS Looked At | What You Add Now | How You Tie It Back |
| FEIE days | Prior statements or partial travel proof | Passport stamps, itineraries, HR letters | Index to Form 4549 line X; Exhibit A‑1 to A‑5 |
| Foreign taxes | Prior FTC calc only | Foreign returns, assessments, payment receipts | Exhibit B‑1 to B‑4 with footnotes in FTC schedule |
| Income verified | 1099s or W‑2s only | Bank credits matched to payroll, contracts | Exhibit C‑1 to C‑3 and corrected wage schedule |
This level of structure helps the IRS screen your request quickly and move it to a substantive review with fewer back‑and‑forth letters.
How To Complete Form 12661 Step By Step
Form 12661 is short, which is why precision matters. The IRS wizard mirrors the fields and allows upload or PDF download. Here is the fast path.
- Taxpayer and case identifiers Enter legal name, SSN or EIN, and the exact tax year. Add the IRS office from your 3338‑C letter if available.
- Dispute blocks, one per issue For each disputed item, enter the description exactly as it appears on Form 4549, a short written reason why you disagree with the audit results, the amount claimed on the original return, and the amount allowed on the audit report. Keep the narrative short and factual, then point to numbered exhibits.
- Attach supporting documents Upload or include copies only, labeled with the same dispute numbers you used on the form. Put the TIN and year on every page.
- Review, sign, and submit Sign the cover letter or accompanying audit response (Form 12661 itself has no pre-printed signature block – the signature lives on the cover letter or amended return that accompanies the disputed-issue list) and include direct contact details with best times to call. If you file electronically through the wizard, download the PDF copy for your records before you close the session.
Where And How To Submit Form 12661
- Digital: Use the Document Upload Tool at irs.gov/examreply when enabled by your exam unit. It is the IRS’s recommended channel for correspondence examinations.
- Mail: Send to the address on your audit letter. If you are unsure, call the numbers in the IRS guidance to confirm the correct destination. Consider certified mail with return receipt.
- Fax: Use the number on the notice and put your TIN and tax year on every page to ensure proper association.
There is also a public IRS DMAF page for Form 12661 that guides you through the same inputs and lets you submit electronically or download the completed PDF, which is handy for internal reviews.
After You File, What To Expect, Holds, And Appeals
Most taxpayers receive an acknowledgment or early contact in roughly 30 days, but complex cases can extend for several months. During reconsideration, collections can continue unless the IRS places a hold, so keep an eye on transcripts, deadlines, and client communications. If the IRS allows your position, the agency will abate the assessment and related penalties or interest as applicable. If you disagree with the outcome, you can request an Appeals conference. If the balance has been paid, you can pivot to a refund claim.
The IRS highlights new information as the central requirement, and it recommends the Document Upload Tool for faster handling of correspondence cases. Build your package to that expectation.
Quick Comparison, Choosing The Right Path
| Situation | Path | Notes |
| Unpaid assessment, closed audit, new documents | Form 12661, Audit Reconsideration | Send to the exam office, include Form 4549 and targeted exhibits. |
| Final court decision or binding closing agreement | Reconsideration not available | Closing agreements under IRC 7121 carry statutory finality. |
| Fully paid | File refund claim, generally via Form 1040‑X | Do not file Form 12661 when fully paid. |
| Processing or computational error | Reconsideration with proof | Clearly show the error and corrected computation. |
A Repeatable Firm Workflow That Saves Review Time
Here is a simple playbook you can drop into your firm’s SOPs:
- Intake checklist: confirm eligibility, unpaid status, and presence of new information.
- Evidence sprint: assign a preparer to gather precise documents by dispute, while a senior builds the cross‑reference index and corrected calcs.
- Review pass one: quality reviewer checks that every Form 4549 line in dispute has a matching exhibit and a corrected amount.
- Packaging: assemble mail, fax, or digital upload sets with consistent file names and page labels for TIN and tax year.
- Tracking: log acknowledgment dates, collector actions, and follow‑ups in your workflow tool.
Where Accountably Can Help, Briefly
If your team is buried in production, the real choke point is often documentation discipline, not tax knowledge. This is a place where a controlled offshore delivery system helps you standardize workpapers, enforce cross‑referencing, and keep review time low, all inside your systems and templates. Use that structure to turn reconsiderations into a clean, repeatable process, not an all‑hands fire drill.
Common Mistakes We See Every Season
From my side of the desk, the same handful of errors show up on almost every Form 12661 package, and each one is fixable with a quick SOP tweak.
Reusable Checklists
These three checklists are copy-paste ready for the firm SOP library. Use them every time a reconsideration package goes out the door.
Eligibility and Intake Screen
- Pull Form 4549 and confirm the audit is closed.
- Confirm tax for the disputed year is unpaid. Fully paid cases pivot to a refund claim on Form 1040-X, not Form 12661.
- Confirm no Tax Court decision or binding closing agreement covers the disputed items.
- Verify there is new information or evidence the auditor did not previously review.
- Log the IRS letter date and any response window stated on it.
- Identify the exam office that handled the original audit (this becomes the submission destination).
- Confirm taxpayer identification fields are clean: taxpayer name, tax period, Social Security Number or EIN.
Reconsideration Package Assembly
- Download a fresh Rev. 10-2015 copy of Form 12661 from www.irs.gov and confirm catalog number 29360J on the footer.
- Draft a one-page cover letter referencing Form 4549 and listing each disputed issue by number.
- Complete one disputed-issue block per adjustment. The form prints three blocks per sheet, photocopy additional sheets if more issues exist.
- For every block, fill all four fields: disputed issue or adjustment, reason for disagreement, amount claimed on original return, amount allowed on audit report.
- Number every attached photocopy to match its block (Issue 1, Issue 2, Issue 3, and onward).
- Confirm only photocopies leave the office. Originals stay in the client file.
- Attach a copy of Form 4549 to the front of the package.
- Add taxpayer phone and email on the cover letter so the IRS can reach the practitioner of record.
Post-Submission Tracking
- Submit via the IRS Document Upload Tool for correspondence handling, with mail and fax as fallbacks to the exam office.
- Log the submission method, date sent, and any tracking or confirmation number.
- Diary the initial-acknowledgment window stated in the IRS letter the taxpayer is responding to (per IRS Form 12661, Rev. 10-2015, the form itself does not print a deadline).
- Monitor account transcripts for collection holds and continued enforcement action during reconsideration.
- Note any IRS request for additional documentation and respond inside the stated window.
- Calendar an Appeals conference request if the reconsideration outcome is unfavorable.
- If the disputed balance is paid during the process, pivot the case to a refund claim on Form 1040-X.
Keep 12661 Season From Stalling
Form 12661 work is not seasonal, it is reactive. A Form 4549 lands, the client panics, and the response is suddenly racing a window stated in an IRS letter while the regular review queue is already full. Form 12661 itself does not print a filing deadline (per IRS Form 12661, Rev. 10-2015), so the operative clock is whatever the audit notice or reconsideration acknowledgement specifies, and missing that window pushes the case back toward collections.
The fix is to treat reconsideration as a standing workflow, not an ad-hoc fire drill. A small handful of standards across intake, evidence assembly, and packaging turns a panicked Friday afternoon into a 90-minute production run.
- Lock the intake screen to four gates: closed audit, unpaid balance, new information, and no Tax Court or closing-agreement finality. The screen kills cases where Form 12661 is the wrong vehicle before they enter production.
- Standardize the disputed-issue block so every package shows all four fields populated (issue, reason for disagreement, amount claimed on original return, amount allowed on audit report). A reviewer can scan a templated block in seconds.
- Build a numbered-exhibit convention before evidence collection starts. Every photocopy carries its block number, every time, so attachments cannot drift to the wrong issue.
- Default to the IRS Document Upload Tool for submission, with mail and fax as fallbacks routed to the exam office that handled the audit.
- Calendar the IRS letter deadline and an internal acknowledgement check at intake, not after the package ships.
When the production discipline is in place, reconsideration stops competing with regular compliance work for senior review hours. That is the shift our U.S. taxation services team builds into client workflows: documented SOPs, multi-layer review, and structured workpapers so audit-response packages move on a predictable cadence instead of derailing the week.
FAQs
It is the IRS’s Disputed Issue Verification form used to package an audit reconsideration request after a closed exam with unpaid tax. You list each disputed Form 4549 item, explain why it is wrong, and attach new or previously unreviewed proof.
Prepare a letter or Form 12661, tie every dispute to evidence, and submit via the Document Upload Tool, mail, or fax to the office that handled your audit. Include your contact information and a copy of Form 4549. Expect initial contact in about 30 days, though timelines vary.
Download it from IRS.gov and use it to report sales and dispositions of capital assets. Your broker statements and 1099‑B data will help you match proceeds and basis, then carry totals to Schedule D.
Schedule J is a corporate foreign tax credit schedule, not a Form 12661 requirement. It can matter if your dispute involves FTC calculations. In those cases, attach corrected FTC schedules and foreign tax proof with your reconsideration.
Other forms this guide names
- Form 1040‑X: How to Amend Your Tax Return in 2025
- Form 2555: Foreign Earned Income Exclusion & Housing
Summarize this article with AI
About this guide
Accountably helps US CPA, EA, and accounting firms hire trained accountants and tax preparers in India.
About us Reviewed byJugal Thacker, CPAFounder and CEO at Accountably
A US-licensed CPA with 7+ years inside US firms – PwC, a real-estate tax practice, then a full-service firm, rising from reviewer to manager to advisory. This article was reviewed against current IRS guidance for the 2025 tax year and updated for filers preparing late returns, amendments, and 2026 estimates.
View profile →How we research, review, and update this guide
Every Accountably guide is researched against primary IRS sources, reviewed by a U.S. CPA, and refreshed as guidance evolves. Read our Editorial Guidelines to see how we source, fact-check, and update our content.