A variable cost is one that varies in direct proportion to the level of activity within the business (OpenStax, Basic Cost Behavior Patterns), and determining one means reaching that figure by either of two routes: multiply the variable rate per unit of activity by the activity level, or subtract total fixed cost from total cost at that same activity level. Which route you take depends on what you already hold, a known rate or a known fixed base, and the two agree only when both figures belong to the same level of activity. The harder case is holding neither, where one number carries both parts and has to be taken apart first.
The Two Routes to the Number
Route one runs forward from a rate. That rate is the variable cost per unit of activity, the b in the Y = a + bx total cost equation set out in variable expenses, so this route is that equation’s bx term evaluated at the activity level you care about. Route two runs backward from a total, since total cost equals fixed costs plus variable costs (OpenStax, Principles of Accounting, Volume 2, Estimate a Variable and Fixed Cost Equation and Predict Future Costs), the identity worked through in total cost formula. Where the period’s fixed base is known, the variable amount is whatever remains once that base comes out.
A rate nobody ever quoted can still be derived. A business that knows what is driving a cost can determine its per-unit variable cost from the totals it already holds, by dividing each variable cost by the level of the driver that produced it (OpenStax, Estimate a Variable and Fixed Cost Equation and Predict Future Costs). Whether the cost belongs in that pool at all is settled earlier, by the classification test in fixed or variable costs.
Separating a Mixed Cost
Both routes assume the split already exists, and on a real invoice it usually does not. Sometimes a business will need to use cost estimation techniques, particularly in the case of mixed costs, so that it can separate the fixed and variable components, since only the variable components change in the short run, and the estimation techniques that can be used include the scatter graph, the high-low method, and regression analysis (OpenStax, Estimate a Variable and Fixed Cost Equation and Predict Future Costs).
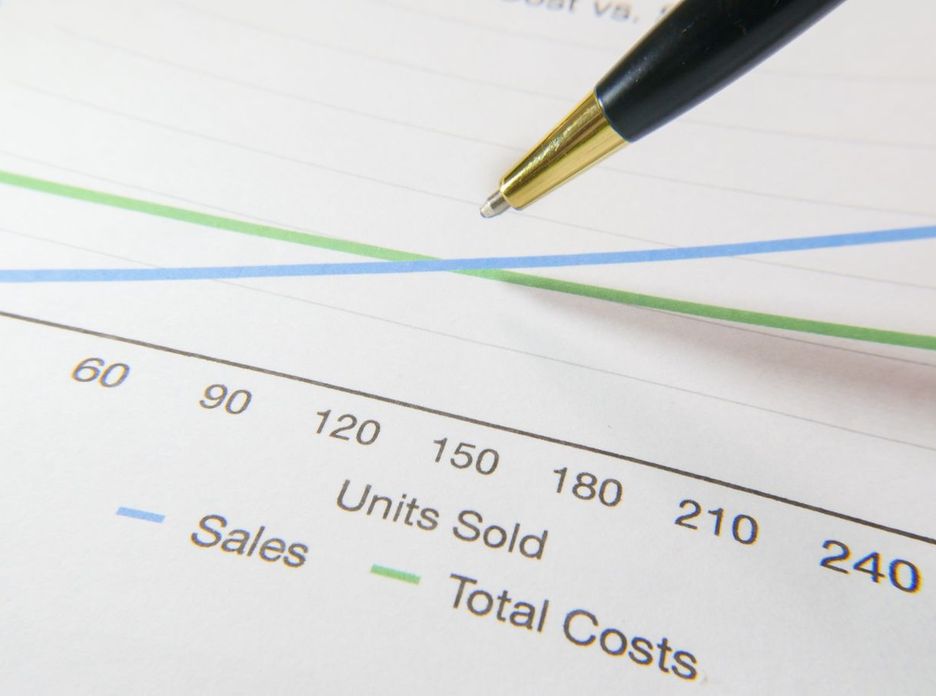
The scatter graph diagnoses rather than estimates. It plots actual costs incurred for various levels of activity under a trend line, and because different people would likely draw different lines, leading to different estimations of fixed and variable costs, its job is only to show whether a linear relationship exists. Where it does not, other methods of analysis are not appropriate (OpenStax, Estimate a Variable and Fixed Cost Equation and Predict Future Costs).
The high-low method turns two of those points into a rate, using the highest and lowest levels of activity and their associated costs. The word activity is where it gets botched: always choose the highest and lowest activity and the costs that correspond with those levels, even if they are not the highest and lowest costs (OpenStax, Estimate a Variable and Fixed Cost Equation and Predict Future Costs). The change in cost divided by the change in activity gives the rate, and the fixed component follows by subtracting the variable component from total cost at either point.
Least-squares regression is the third estimator and the more accurate one, because it minimizes the errors of trying to fit a line between the data points instead of resting on two of them. High-low estimates can vary significantly from actual costs, especially where the high or low activity levels are not representative of the usual level of activity within the business (OpenStax, Estimate a Variable and Fixed Cost Equation and Predict Future Costs).
A Worked Separation
Say a firm’s practice software bills one combined charge covering both access and filing, and the firm has a year of invoices set against returns filed. Its busiest and slowest months supply the two points.
Busiest month        300 returns                     $2,400
Slowest month         80 returns                     $1,080

Variable rate       (2,400 - 1,080) / (300 - 80)  =   $6.00 per return
Fixed component      2,400 - (300 x 6.00)         =     $600
Same at the low      1,080 -  (80 x 6.00)         =     $600

A 150-return month, total charge   600 + (150 x 6.00) = $1,500
A 150-return month, route one      150 x 6.00         =   $900
A 150-return month, route two      1,500 - 600        =   $900
Recomputing the fixed component at the low point returns the same $600, which catches an arithmetic slip and nothing more, because with two points the two answers always agree. Whether the split is trustworthy is the separate question of whether those two months are representative, and once the rate exists both routes answer the original question identically. Route two is what a firm actually uses, since the invoice total is the figure it holds and the rate is the one it had to derive. That answer holds inside the band of activity the two points came from, and outside it the fixed component can step to a new level, which is the relevant-range limit set out in fixed expenses.
What a Variable Cost Figure Is Not
The number this produces is the variable cost of the units already counted, not the cost of the next one, which is marginal cost.
Common Questions
What Determines a Variable Cost?
The cost driver does, rather than the account name or the size of the bill, and what makes a cost variable is set out in variable expenses. It decides both which pool a cost belongs in and what the rate gets multiplied by.
How Do You Find Fixed Cost and Variable Cost?
Out of the same data, but in the reverse of the order the question names. For a mixed cost the variable rate comes first, from high-low or from regression, and the fixed component falls out by subtracting the variable part from total cost at a known activity level (OpenStax, Estimate a Variable and Fixed Cost Equation and Predict Future Costs). Where the two already sit in separate accounts, the sorting test in fixed or variable costs is enough.
How Do You Determine the Total Variable Cost?
Multiply the variable rate per unit of activity by the activity level, or subtract total fixed cost from total cost at that same level. What the answer feeds is the contribution margin each unit of work leaves behind, the contribution margin ratio, and the break-even work in cost-volume-profit analysis.
What Are 5 Examples of Variable Costs?
The list runs by what the business sells, so a manufacturer names raw materials and direct production labor while a practice names per-return filing charges, pay-per-return software and hourly seasonal preparers. Those lines, and the one that looks variable but is not, are in variable expenses.
Accountably places trained offshore accountants and tax preparers inside US CPA and EA firms, and a trial task lets a firm’s own reviewer grade real work before the firm commits a single client file.