Depreciation is reported as an operating expense when the asset is used in administration, offices or selling rather than in producing the goods or services being sold. Where the asset does produce goods, the charge attaches to the units it helped make, sits on the balance sheet as part of inventory, and only reaches the income statement inside cost of goods sold, in whatever period those units are sold. One year’s depreciation on two different assets can land on two different lines of the same income statement.
It is a non-cash charge either way, lowering profit in whatever period it reaches the income statement without moving cash. A cash flow statement therefore adjusts net income for non-cash items such as adding back depreciation expenses (SEC, Beginners’ Guide to Financial Statements), the reconciliation set out in the indirect method, and the charge is one of the four stripped out again in EBITDA.
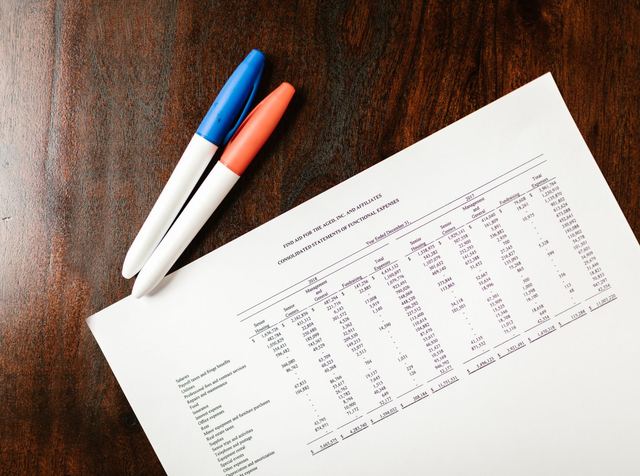
Where it appears on the face of the statement is a presentation choice. The Regulation S-X rule listing the line items that should appear on the face of a filed statement of comprehensive income carries no depreciation caption (17 CFR 210.5-03), so a company may show it on a line of its own or leave it inside selling, general and administrative expenses. The SEC staff fences that choice in two ways. A cost of sales or operating expense line that excludes charges for depreciation, depletion and amortization of property, plant and equipment should say so, with a description reading somewhat as “Cost of goods sold (exclusive of depreciation shown separately below)”, and those charges should not be positioned in the income statement in a manner which results in reporting a figure for income before depreciation (SEC Staff Accounting Bulletin Topic 11, section B).
Operating Expense or Cost of Goods Sold
The separator is written into the SEC’s own description of the statement. Operating expenses are different from costs of sales because operating expenses cannot be linked directly to the production of the products or services being sold, and depreciation is also deducted from gross profit (SEC, Beginners’ Guide to Financial Statements).
The inventory rule pulls the production side back, because cost for inventory purposes takes in the charges indirectly incurred in bringing an article to its existing condition and location (Accounting Research Bulletin No. 43, Chapter 4, Statement 3), and depreciation on the machinery that made it is one of them. Which side of that line a given cost falls is worked through in period versus product cost. Which method produces that book charge is set out in straight line depreciation and accelerated depreciation; the separate tax recovery regime is MACRS, with bonus depreciation layered on it.
What It Is Confused With
Operating expense and capital expenditure. Capital expenditure decides, at the outlay, whether a cost goes on the balance sheet instead of into this year’s profit, so it produces the later charge rather than competing with it, a split worked through in OpEx versus CapEx.
Depreciation expense and accumulated depreciation. One is a period figure on the income statement, the other a running total carried against the asset in a contra account, which reduces the assets it sits among, so it never appears among operating expenses (where accumulated depreciation goes on a balance sheet).
The book charge and the tax deduction. The book charge spreads the cost of the asset over the periods it is used (SEC, Beginners’ Guide to Financial Statements), while the tax deduction for tangible property is determined by using the applicable depreciation method, the applicable recovery period and the applicable convention (26 U.S.C. 168(a)), so one asset carries two different numbers for the same year, and the entry that holds both is depreciated.
Common Questions
Should Depreciation Be Included in COGS?
To the extent it belongs to production, yes. For financial reporting the test is the inventory cost rule: depreciation on the machinery that made the goods is one of the charges indirectly incurred in bringing an article to its existing condition and location (Accounting Research Bulletin No. 43, Chapter 4, Statement 3), so it reaches income inside cost of goods sold when those goods sell. Selling expenses constitute no part of inventory costs, and general and administrative expenses are period charges except for the portion clearly related to production (Accounting Research Bulletin No. 43, Chapter 4, paragraph 5A), so depreciation on assets serving administration or selling stays outside it.
For tax the same split runs on a separate rule, and only for the taxpayers it reaches. Cost recovery, which includes depreciation, amortization and cost recovery allowances on equipment and facilities (Treasury Regulation 1.263A-1(e)(3)(ii)(I)), is one of the indirect costs a taxpayer subject to section 263A must capitalize when it is properly allocable to property produced or property acquired for resale (1.263A-1(e)(3)(i)(A)). A taxpayer that meets the section 448(c) gross receipts test, and that is not a tax shelter barred from the cash method, is not required to capitalize those costs under section 263A for that taxable year (1.263A-1(j)(1)).
How Do You Record a Depreciation Expense?
One entry each period, a charge for that period’s allowance and the same amount added to accumulated depreciation. Which line the charge half reaches depends on what the asset does for the business, and the entry is set out in depreciated.
What Are Examples of Depreciation Expenses?
The SEC names the wear and tear on assets such as machinery, tools and furniture, used over the long term (SEC, Beginners’ Guide to Financial Statements). In a CPA firm they are usually the workstations the staff work on, the office furniture, and improvements to leased space, none of which touch production.
How Does Depreciation Work on a P&L?
It reduces profit in the period the charge reaches the statement without reducing cash. The production share sits above the gross profit subtotal inside cost of sales and the rest below it among operating expenses, so one annual charge moves gross profit and operating income by different amounts, the subtotal set out in the equation for operating income.
Firms that lose review time splitting a client’s depreciation between cost of sales and operating expenses can put a block of that work through Accountably’s trial task.