Summarize this article with AI
In Brief
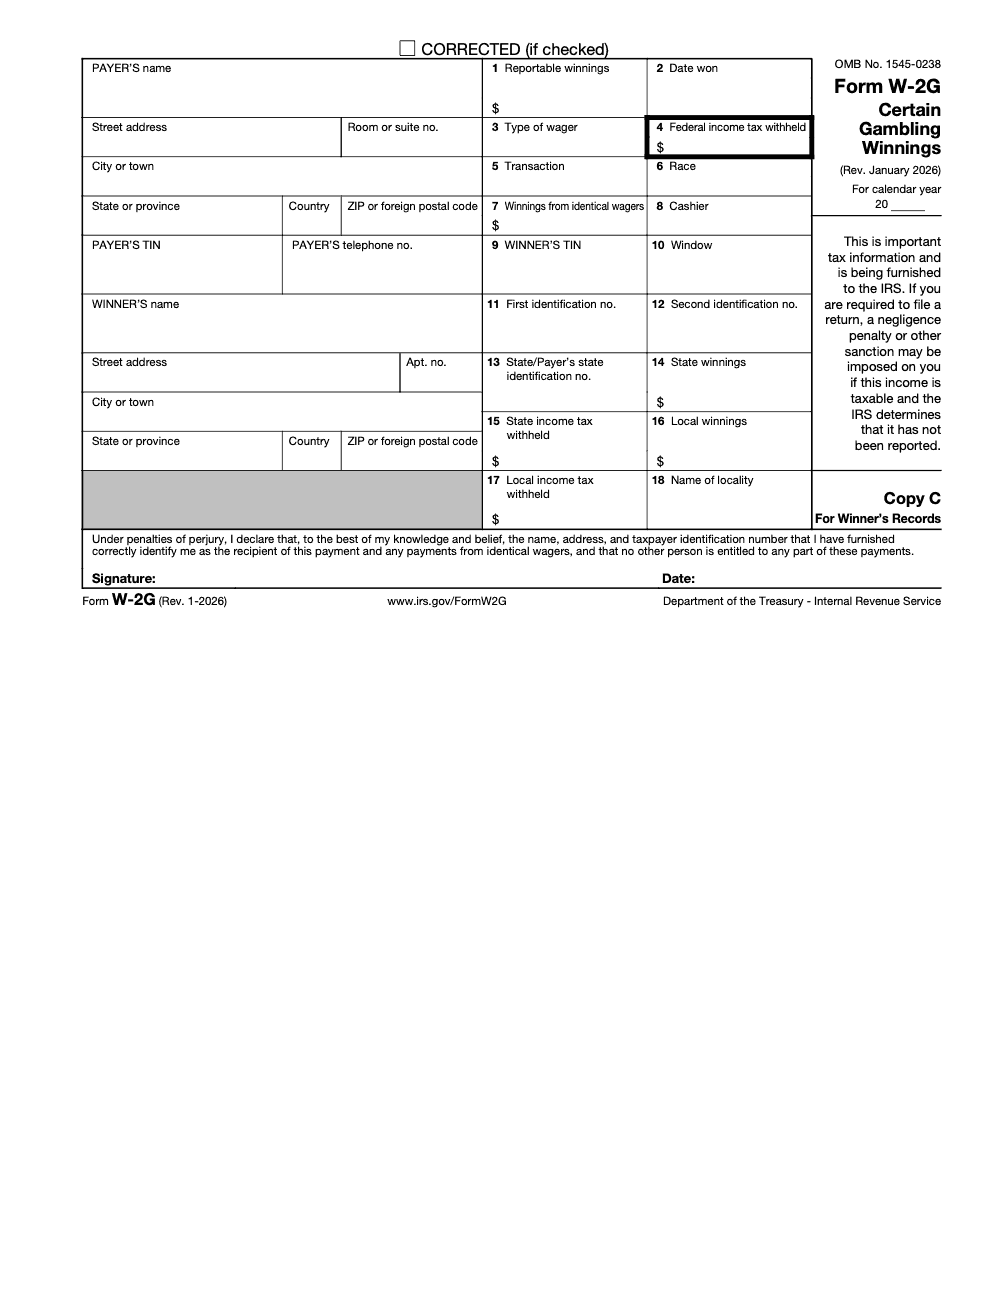
Form W‑2G, Certain Gambling Winnings, is the information return a payer issues to report gambling winnings and any federal income tax withheld (Form W‑2G, Rev. January 2026). The dollar trigger is type-specific and set out in IRS Publication 1099, and a W‑2G is also required any time federal tax is withheld. Winners report the income on Schedule 1 of the individual income tax return, claim the Box 4 federal withholding with their other payments, and, if they itemize, deduct gambling losses on Schedule A up to total winnings (limited to 90% of losses beginning in 2026).
A new client handed over a stack of slot W-2Gs from one weekend and nothing else, sure he could subtract what he lost on the floor and report the difference. Winnings and losses are reported separately: the income goes on Schedule 1, losses are deductible on Schedule A if you itemize, and you must still report all gambling income, even if no form arrives.
Form W-2G, Certain Gambling Winnings, is the information return a payer issues, and the dollar trigger is type-specific: $1,200 for slots and bingo, $1,500 net for keno, over $5,000 net for poker tournaments, and $600 or more at 300 times the bet for horse races and many other wagers. Federal withholding is usually 24% on certain large payouts, and winners claim the Box 4 withholding with their other payments.
Key Takeaways
- You receive Form W‑2G when certain gambling winnings meet IRS reporting rules or when any federal tax is withheld. You must still report all gambling income, even if no form arrives.
- Common thresholds: 1,200 for slots and bingo, 1,500 net for keno, over 5,000 net for poker tournaments, and 600 or more at 300× the bet for horse races and many other wagers.
- Federal withholding is usually 24% on certain large payouts. Backup withholding is 24% if you do not give a valid TIN. Withholding and backup withholding do not apply at the same time.
- On your tax return, report gambling income on Schedule 1, then claim any W‑2G federal withholding with your other withheld tax payments. Itemize on Schedule A to deduct your losses, never more than your winnings (beginning in 2026, the One Big Beautiful Bill Act limits the gambling loss itemized deduction to 90% of losses). (Winnings go on the "Other income" line of Schedule 1, and W‑2G federal withholding flows to the federal income tax withheld line on Form 1040. Check the current year instructions for the exact line numbers when you file.)
What is Form W‑2G and who sends it
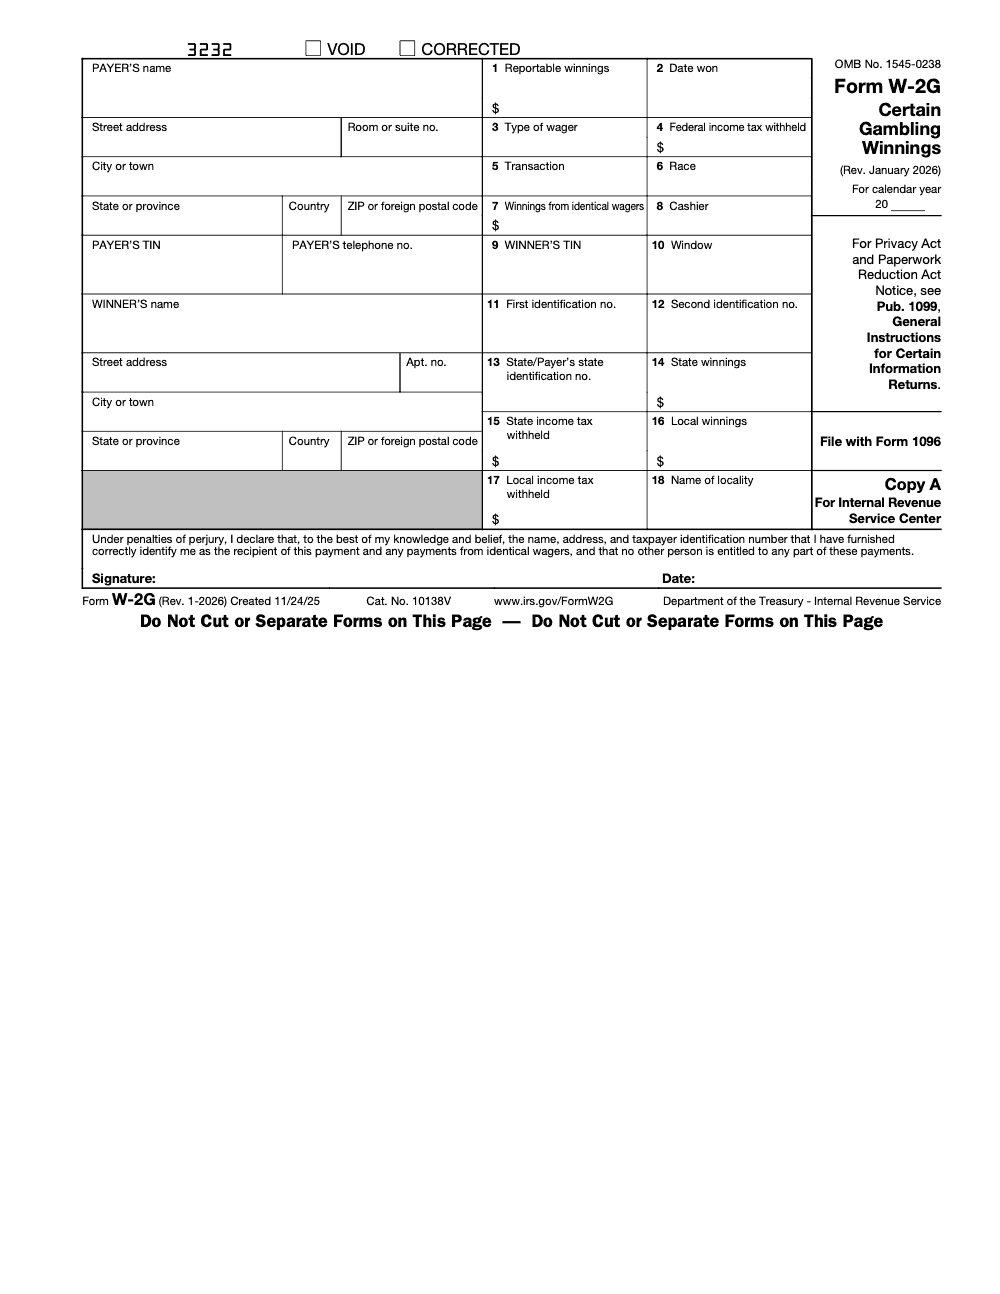
Form W‑2G is an IRS information return. Casinos, lotteries, racetracks, sportsbooks, and similar payers use it to report certain gambling winnings and any federal income tax they withheld. You get a copy, the IRS gets a copy, and your tax software expects you to enter what appears in those boxes. The form shows your gross winnings or the fair market value of a noncash prize, the wager type, the date, and your identifying information, along with any federal, state, or local tax withheld.
Even if you never receive a W‑2G, you must report gambling income on your return. The thresholds control when a payer must issue the form or withhold tax, not whether you owe tax on winnings.
When you will receive a W‑2G, thresholds by game
You get a W‑2G when the game specific threshold is hit or any time federal tax is withheld. Here are the core triggers most players run into.
Quick reference table, common W‑2G triggers
| Game or wager type | Reporting trigger for W‑2G | How the amount is measured |
| Slots, Bingo | 1,200 or more | Gross payout per game session |
| Keno | 1,500 or more | Net payout, payout minus the wager for that winning game |
| Poker tournament | Over 5,000 | Net of the buy in and entry related amounts |
| Horse races and many other wagers | 600 or more and at least 300× the bet | Usually measured on a per ticket basis, special rules apply to pari mutuel pools |
These thresholds come directly from the IRS instructions for Forms W‑2G and 5754, which the IRS maintains as a continuous use reference. The numbers have remained stable in recent years.
Slots, bingo, and keno, what actually triggers the form
- Slots and bingo, a single game session at 1,200 or more is reportable and a W‑2G is issued. The payer reports the gross payout amount.
- Keno, a W‑2G is issued when your net payout hits 1,500 or more, which means the casino subtracts the cost of the winning keno ticket before testing the threshold.
You still report all gambling income at tax time, even for smaller wins that never generated a form. Keep a running log and the tickets that support your entries.
Horse races and poker, how their limits work
Pari mutuel horse race wins often hit the 300× multiple, which is why you see W‑2G forms at relatively modest dollar amounts. You get a W‑2G when your payout is 600 or more and at least 300 times the original bet. If your proceeds, winnings minus the wager, exceed 5,000 and the bet meets the 300× test, regular 24% federal withholding can apply and will appear in Box 4. Confirm the current dollar triggers in the IRS Instructions for Forms W‑2G and 5754, since those thresholds are not printed on the form itself.
Poker tournaments are different. You receive a W‑2G when your net tournament winnings, payout after subtracting the buy in and certain entry related amounts, are more than 5,000. If tax is withheld, you will see it in Box 4.
Small note for the record, pari mutuel rules include details for “identical wagers” and ticket aggregation that can affect how a track or off track facility calculates the test. This is niche, yet it matters on big days at the races.
How to read the form, the boxes that matter most
Start with the top third of the form and the four boxes that steer your tax reporting.
- Box 1, gross winnings, this is the taxable amount for the prize, cash or fair market value for noncash. This is what you include in income.
- Box 3, type of wager, helps you match the record to the game and verify the correct reporting rule was used.
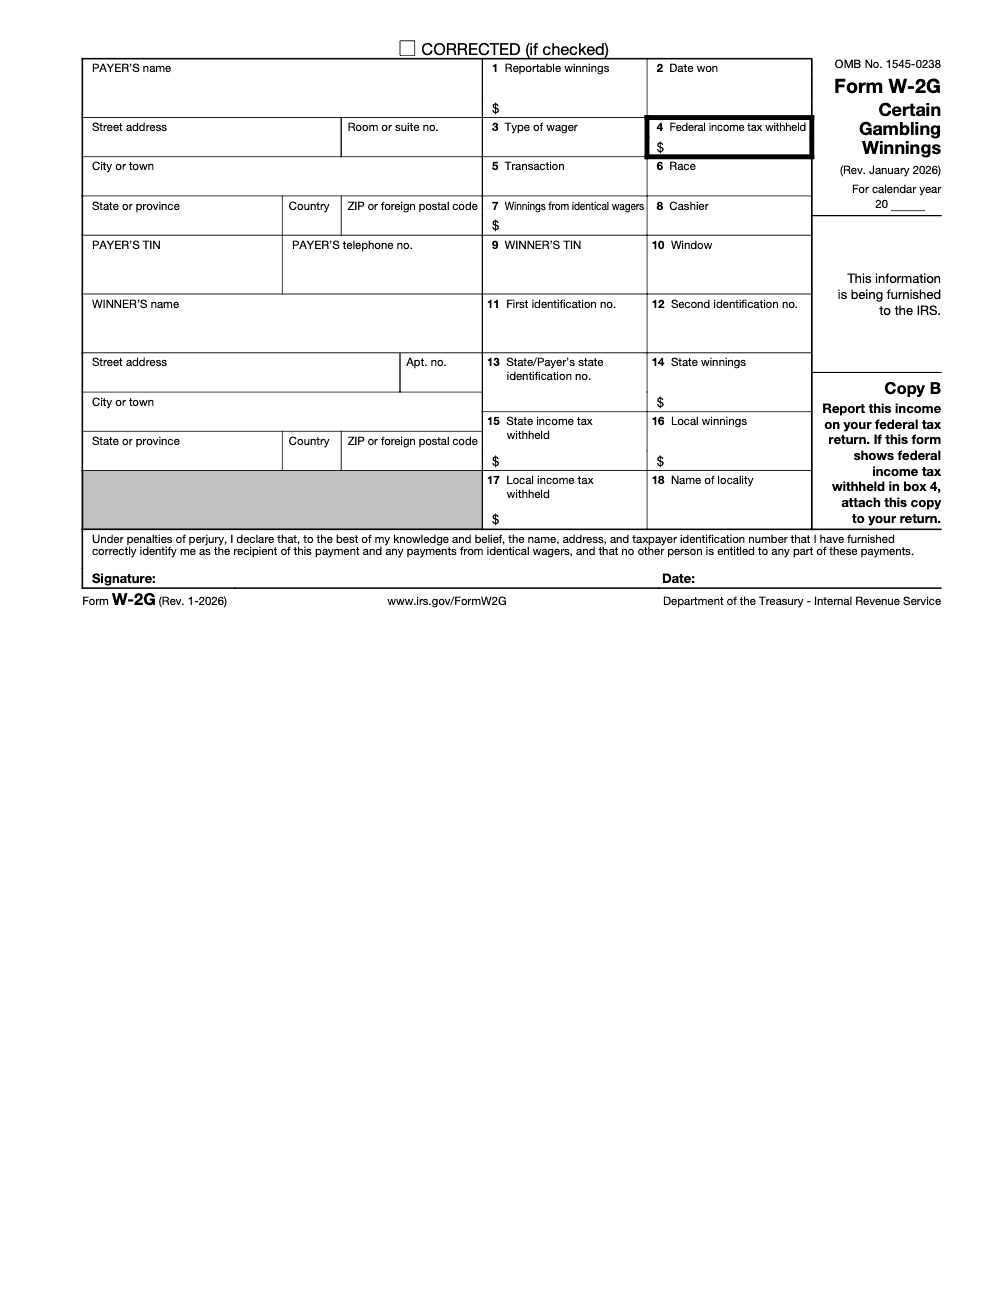
- Box 4, federal income tax withheld, claim this with your other withholding on your Form 1040.
- Boxes for your name and SSN or ITIN, always double check these at the window so your return matches the IRS copy. If you did not provide a valid TIN, backup withholding at 24% can apply.
Tip from the trenches: check the “date won” on the form. It should match the date the wager paid off, not when the envelope was mailed. This keeps your log, your bank statement, and your tax return in sync.
Wager and date fields, why they matter
The payer uses the wager type and the win date to determine whether a W‑2G was required and whether withholding applied. For horse races and other 300× situations, that classification affects both the threshold and any regular withholding decision. For noncash prizes, fair market value drives the numbers in Box 1 and any withholding calculation.
Withholding rules on gambling winnings, what applies and when
There are two federal systems to know, regular gambling withholding and backup withholding. You will never have both on the same payment.
- Regular withholding at 24% applies when your proceeds are more than 5,000 from lotteries, sweepstakes, wagering pools, and certain other bets that meet the 300× test. This includes certain pari mutuel horse race wins. Confirm the current dollar thresholds in Pub. 1099 and the Instructions for Forms W‑2G and 5754, as they are not stated on the form itself.
- Backup withholding at 24% kicks in when you do not furnish a correct TIN, and the win meets the applicable dollar test for that game, for example 1,200 slots or 1,500 keno. Backup withholding can also apply to poker tournaments and other wagers that meet the dollar rules but were not otherwise subject to regular withholding.
Noncash prizes, cars and trips, are valued at fair market value. If the payer withholds but pays the tax on your behalf instead of collecting it from you, the IRS requires a gross up that raises the effective withholding above the stated rate, because the tax the payer covers is itself treated as additional winnings. This surprises many winners, so it is worth checking before you drive off the lot.
Simple examples you can model in your records
- Lottery lump sum, you win 20,000 on a 10 ticket. Proceeds exceed 5,000 and the 300× test is met, so the payer withholds 24% of the 19,990 proceeds and reports it on your W‑2G. You include the full 20,000 in income and claim the Box 4 amount with your other withholding.
- Slot jackpot at 6,000, slots are not subject to regular withholding, but if you fail to provide a valid SSN or ITIN, expect 24% backup withholding. Box 1 shows 6,000, Box 4 shows the withheld tax.
- Car worth 30,000 from a sweepstakes, the payer asks you either to bring in the tax on the prize’s taxable value or to authorize a grossed-up amount if they cover it. Either way, Box 1 shows the prize value, and Box 4 shows the tax withheld.
Where to report winnings and how to claim losses
For individual filers who are not in the trade or business of gambling, report gambling income on Schedule 1 with your other income items, then claim any federal tax withheld from W‑2G in the payments section of Form 1040. Winnings go on the "Other income" line of Schedule 1 and the federal withholding flows to the federal income tax withheld line on Form 1040, so always confirm the current year line numbers when you file.
If you itemize, you may deduct your gambling losses on Schedule A, but the amount you deduct cannot be more than your reported winnings (beginning in 2026, the One Big Beautiful Bill Act also caps the deduction at 90% of losses). Keep receipts, tickets, and a contemporaneous win loss log so you can substantiate the deduction if asked.
Quick rule you can trust: report every dollar of wins, then, if you itemize, deduct losses separately, never more than your wins. Keep the paper trail.
Recordkeeping, simple habits that prevent headaches
A clean paper trail is your best defense against IRS mismatch notices and your fastest path to a smooth refund.
- Keep a win loss log with date, game or wager type, location, amounts bet and won, and ticket or slip numbers.
- Save W‑2G forms, payout slips, bank statements for larger deposits, and fair market value documentation for noncash prizes.
- Enter each W‑2G separately in your software so totals match Boxes 1 and 4.
- Provide a correct SSN or ITIN to avoid 24% backup withholding.
If a payer withheld too much, you reconcile it when you file and may get a refund. If too little was withheld or none at all, consider estimated tax to avoid underpayment penalties. Publication 505 explains how the 24% withholding fits into your annual tax picture.
Practical scenarios you can copy
- You win 6,000 on a slot machine, the casino may or may not withhold, slots generally are not subject to regular withholding. You receive a W‑2G showing 6,000 in Box 1. You report the 6,000 on Schedule 1. If you had 2,500 of documented losses this year and you itemize, you can deduct that 2,500 on Schedule A, never more than your winnings. If Box 4 shows any federal withholding, you claim it with your other withholding on Form 1040.
- You win 8,000 in a poker tournament after a 1,000 buy in, your net is 7,000, which is over 5,000, so you receive a W‑2G. If the payer withheld, you will see 24% in Box 4. Report the income and claim the withholding.
- You split a winning ticket with friends, ask the payer for Form 5754 so each person receives their own W‑2G. This prevents one person from being stuck reporting the full amount.
A brief note for firms
If you run a CPA or EA firm, you already know the pain comes from delivery, not demand. Clean workpapers and consistent SOPs cut review time on W‑2G heavy returns. If you need standardized workpaper prep, naming, version control, and trained offshore capacity that works inside your systems, Accountably places trained offshore preparers inside your systems with multi-layer review, so your team can focus on client strategy while we keep production steady and secure. Use this only if it genuinely helps your workflow, not as a shortcut for tax judgment.
Bottom line
You can make W‑2G reporting easy. Confirm your information at the window, keep a simple win loss log, and know when 24% withholding or backup withholding applies. When tax time comes, report every dollar of winnings, claim Box 4 withholding, and, if you itemize, deduct your losses, never more than your winnings (the One Big Beautiful Bill Act caps the deduction at 90% of losses beginning in 2026). As of November 28, 2025, the thresholds and rates above reflect current IRS guidance. Always check the latest IRS instructions if your filing spans a new year.
This article reflects IRS guidance available as of November 28, 2025. For thresholds, withholding rules, and line references, see the IRS Instructions for Forms W‑2G and 5754, Publication 505, and Topic No. 419.
Common Mistakes We See Every Season
The W‑2G itself is simple to read, but the reporting around it is where returns go sideways. Here are the patterns my team flags every season.
Reusable Checklists
These are copy-paste ready for your firm SOPs. Drop them into your workpaper template and confirm the line references against the client's filing year.
W‑2G intake packet
- Collect every W‑2G the client received, including digital copies pulled from player accounts.
- Confirm the name and Box 9 TIN on each form match the return to avoid IRS document-matching notices.
- Gather payout slips, player statements, and fair market value documentation for noncash prizes.
- Ask about wins that produced no W‑2G, since those are still reportable income.
- Flag any form showing federal tax in Box 4 so the credit is not lost.
- Mark shared or pooled tickets that may need Form 5754.
Return entry and reconciliation
- Enter each W‑2G at the gross Box 1 amount on Schedule 1, never a netted figure.
- Carry Box 4 federal withholding to the federal income tax withheld line on Form 1040.
- Confirm whether regular 24% withholding or backup withholding applied to each payment.
- For nonresident alien winners, confirm the winnings were reported on Form 1042-S rather than W‑2G.
- Reconcile total winnings entered against the sum of all Box 1 amounts.
- Check the current year IRS instructions for the exact Schedule 1 and Form 1040 line numbers.
Loss deduction substantiation
- Confirm the client is itemizing on Schedule A before claiming any loss.
- Apply the 90% loss limit for 2026 and later years, and cap the deduction at total reported winnings.
- Tie each loss figure to a dated win-loss log and supporting tickets or statements.
- Retain documentation per IRS Publication 529 in case of examination.
- Do not net losses against winnings on the income side of the return.
Keep W2G Season From Stalling
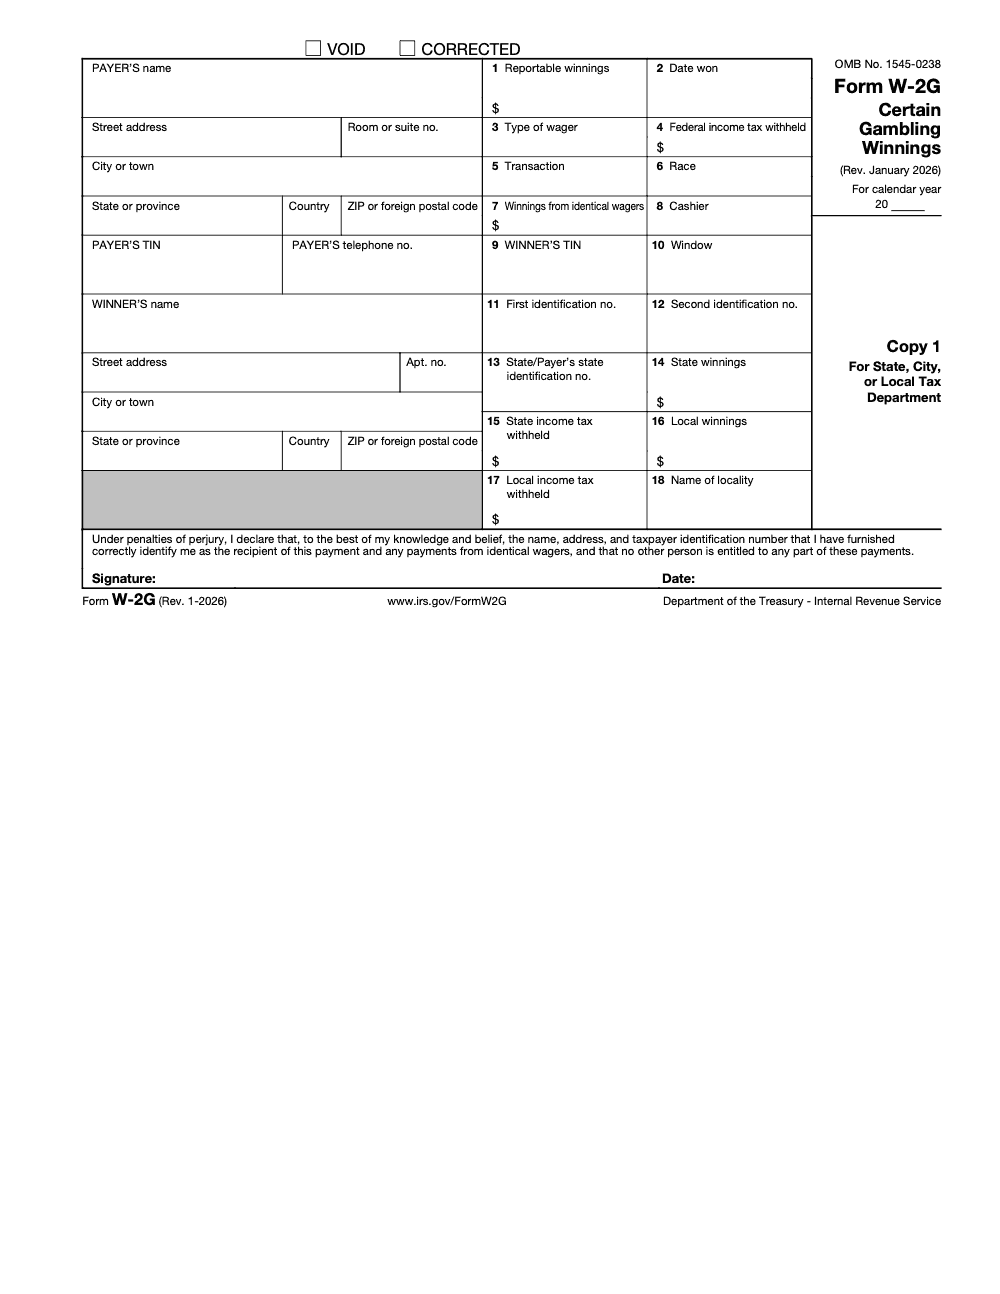
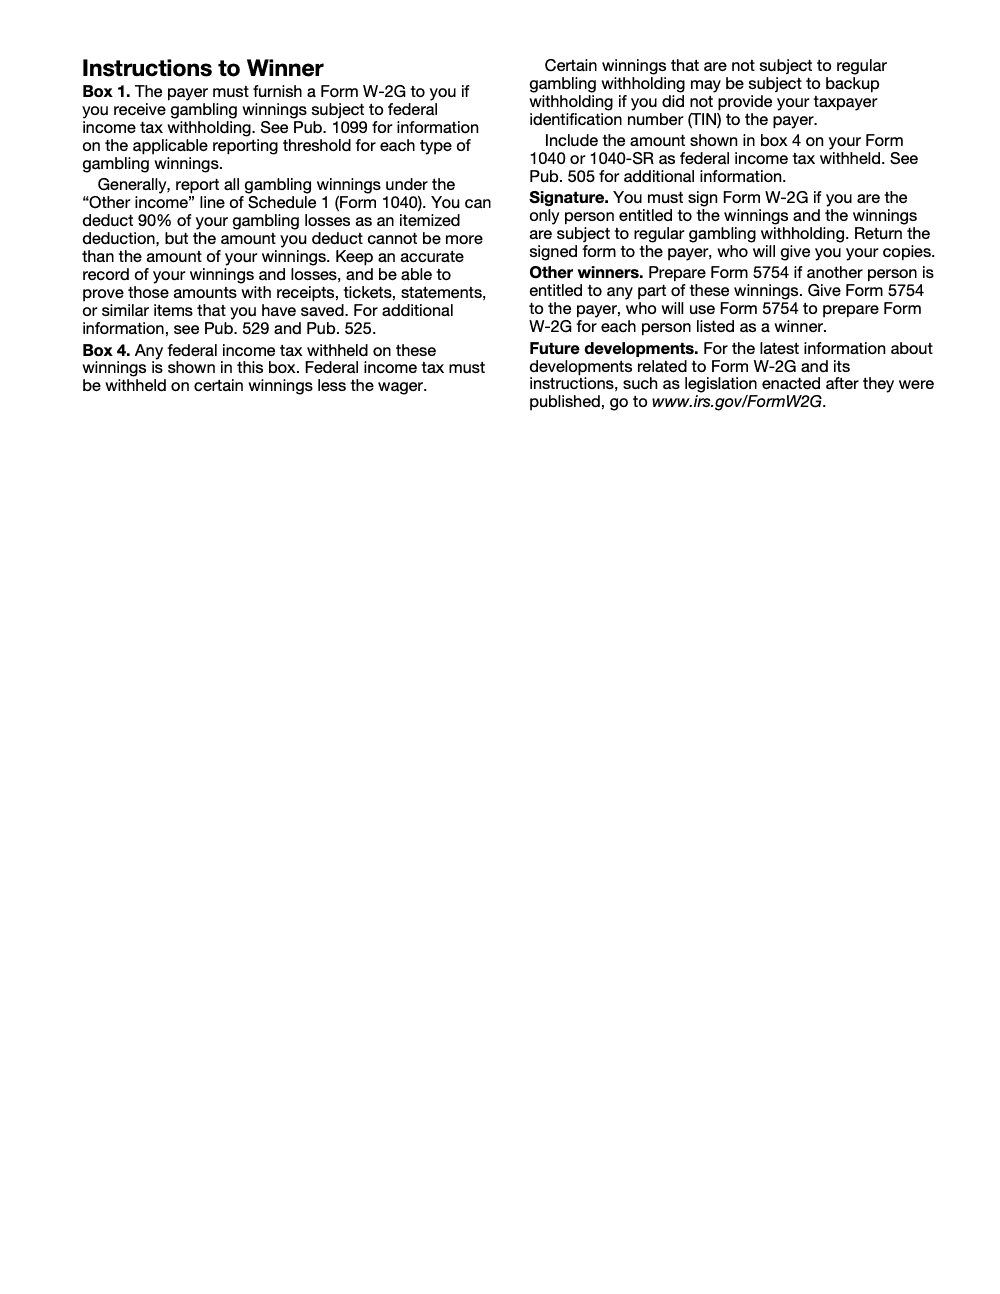
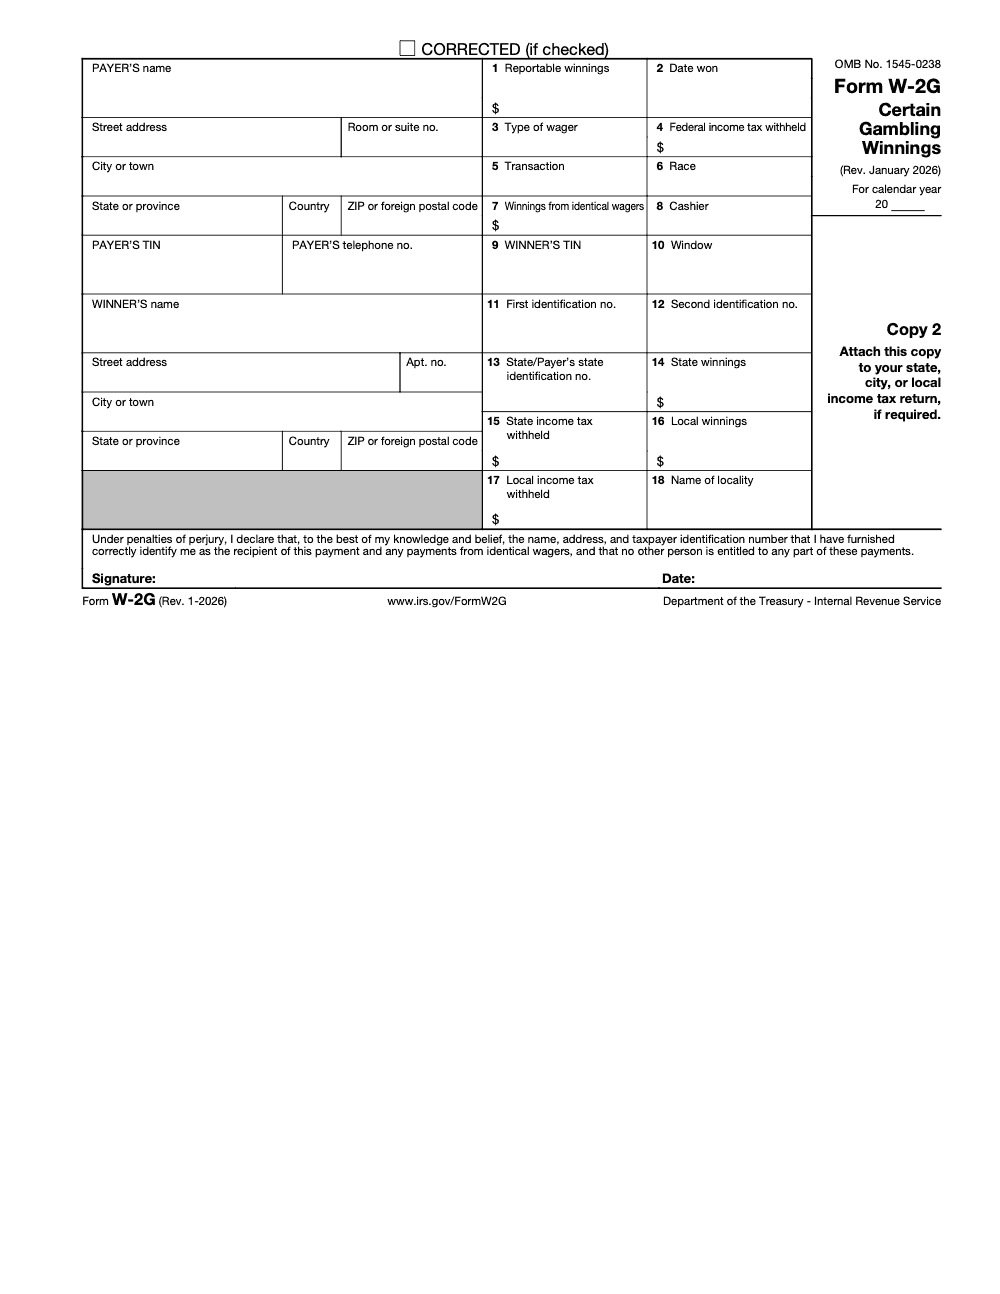
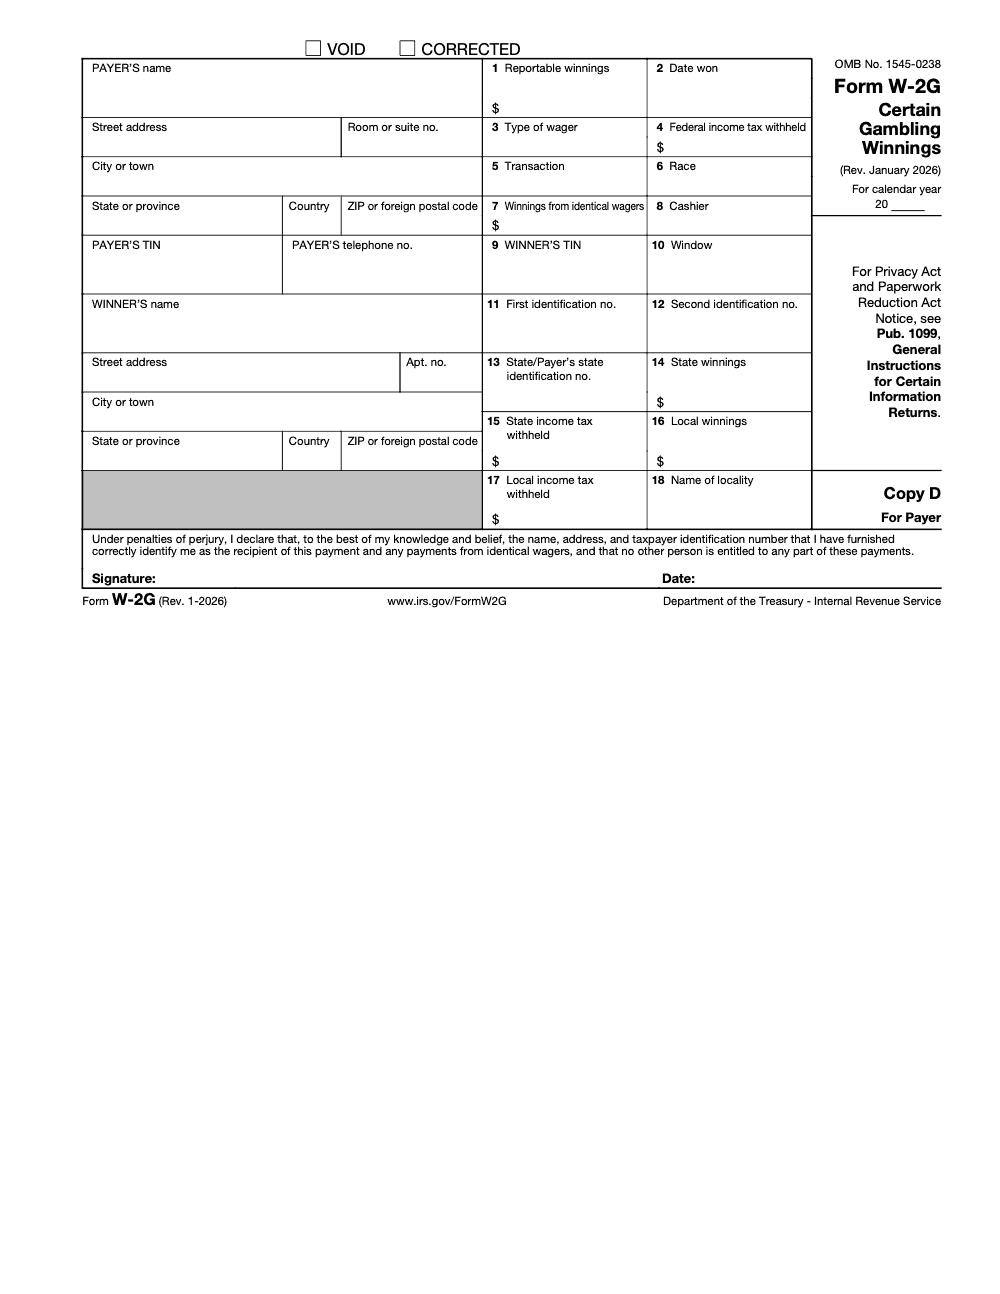
Form W‑2G looks small, but a complete set runs to six separate copies, Copy A, 1, B, C, 2, and D, routed to the IRS, the state or local tax department, the winner, and the payer's own file (Form W‑2G, Rev. January 2026). On a busy gaming floor or a year-end batch, that volume plus eighteen numbered boxes per form is where reporting backs up and reconciliation slips.
The fix is not heroics at the deadline, it is structure ahead of the rush. When intake, data entry, and review each follow a written step, W‑2G volume stops being a fire drill and becomes a predictable queue your team can clear without late nights.
- Standardize how every W‑2G is captured so Box 1 winnings and Box 4 withholding are keyed once and reconciled against the client's own slips.
- Verify the winner name and Box 9 TIN at intake, since a mismatch is what later triggers an IRS document-matching notice.
- Route Copy A filings with Form 1096 and Copy 1 to the correct state or local department on a tracked schedule, not from memory.
- Keep the loss workpaper separate from the income entry so the Schedule A limit (90% of losses from 2026) is applied deliberately, never netted against winnings.
- Flag pooled or shared tickets for Form 5754 before anyone signs, so each winner gets a correctly allocated W‑2G.
This is repeatable production work that does not need a partner's hours, only a disciplined process. Accountably builds that structure into your tax workflow with documented SOPs, multi-layer review, and trained offshore capacity, so W‑2G season moves on schedule and your reviewers stay focused on judgment.
FAQs
It documents certain gambling winnings and any federal income tax withheld, and it helps the IRS match what payers reported to what you file. You still must report all gambling income whether or not you got a W‑2G.
Many reportable wins have no automatic withholding, for example slots, but others can trigger 24% federal withholding when proceeds exceed 5,000 or you did not provide a valid TIN. Your final tax depends on your total annual income and deductions. States may also tax winnings.
No. Report the full amount of winnings, then if you itemize, claim losses on Schedule A. Losses are deductible only up to your total winnings, and beginning in 2026 the One Big Beautiful Bill Act also caps the deduction at 90% of your losses. Keep contemporaneous records.
Yes. Noncash prizes are included at fair market value. If withholding applies and the payer pays the tax on your behalf rather than collecting it from you, gross up rules raise the effective withholding above the stated rate, because the tax the payer covers is itself treated as additional winnings.
Enter winnings on the "Other income" line of Schedule 1 with your other income items, then claim Box 4 federal withholding on the federal income tax withheld line of Form 1040 with the rest of your withholding. Always check the current year instructions for the exact line numbers.
Other forms this guide names
Summarize this article with AI
About this guide
Accountably helps US CPA, EA, and accounting firms hire trained accountants and tax preparers in India.
About us Reviewed byJugal Thacker, CPAFounder and CEO at Accountably
A US-licensed CPA with 7+ years inside US firms – PwC, a real-estate tax practice, then a full-service firm, rising from reviewer to manager to advisory. This article was reviewed against current IRS guidance for the 2025 tax year and updated for filers preparing late returns, amendments, and 2026 estimates.
View profile →How we research, review, and update this guide
Every Accountably guide is researched against primary IRS sources, reviewed by a U.S. CPA, and refreshed as guidance evolves. Read our Editorial Guidelines to see how we source, fact-check, and update our content.